
Choosing a UK bank account as a new immigrant is a critical first step to managing your salary, rent, and everyday expenses. Navigating proof-of-address requirements can be challenging when you first arrive, but selecting the right bank depends heavily on your specific documentation, multi-currency needs, and preference for in-person support.
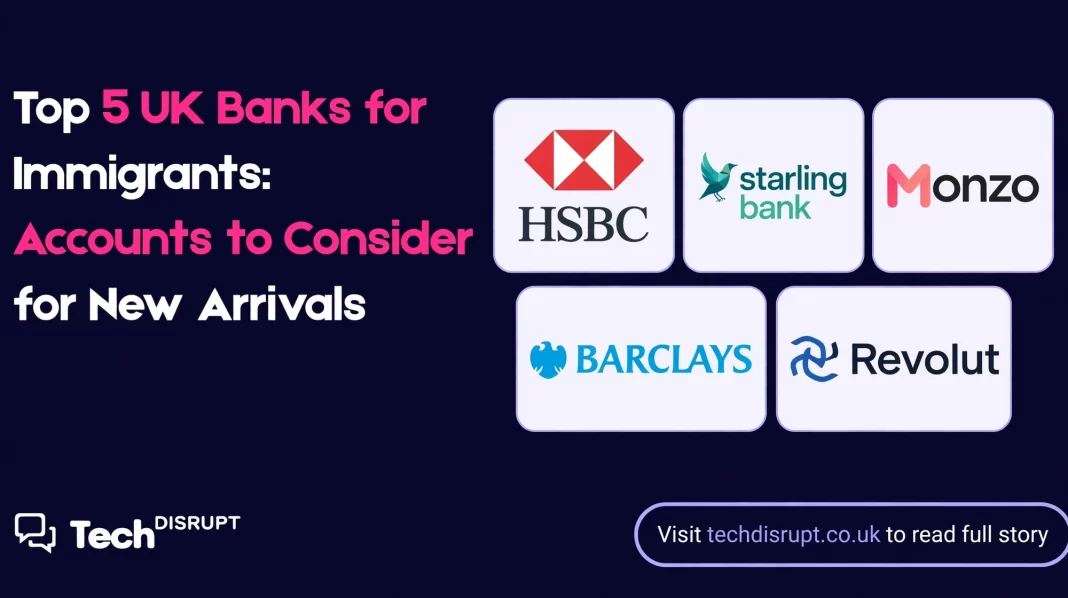
The following guide by TechDisrupt is a list of the top five UK banking options for newcomers.
Here are five UK banking options worth considering if you have just moved to Britain.
1. HSBC UK — Best for Pre-Arrival Setup
Why immigrants choose it:
- Accepts over 12 forms of identity.
- Allows 90 days to provide UK address proof.
Accounts to consider:
- HSBC Basic Bank Account: Free account with no credit check, no monthly fee. Accepts almost anyone with a valid visa.
- HSBC Standard Bank Account: Free daily banking post-arrival.
- HSBC Expat / International Account: Free but requires a £25k+ balance.
Features that matter:
- Over 1,500 branches for in-person help.
- Credible statements for landlords and employers.
- Global View app integration for international accounts.
Downsides:
- Slow to approve, taking up to three weeks.
- High fees for outbound international transfers.
2. Starling Bank — Best for free everyday banking with no hidden fees
Why immigrants choose it:
- Zero monthly fee or hidden charges.
- No UK credit history required to apply.
- Includes a dual GBP and Euro account.
Accounts to consider:
- Personal: Free account with no foreign exchange fees.
- Joint: Free option for relocating couples.
- Business: Free tier for freelance or contract workers.
Features that matter:
- Uncapped fee-free spending when travelling abroad.
- In-app tools to generate council proof-of-address letters.
- Cash deposits available via local Post Office branches.
Downsides:
- Entirely digital banking with no physical branch access.
- Strict initial limits on overdrafts for new arrivals.
3. Monzo — Best for speed upon arrival
Why immigrants choose it:
- No formal credit check required.
- Requires only a passport and UK delivery address.
- Identity verification takes less than 15 minutes.
Accounts to consider:
- Monzo Personal: Free account with core budgeting tools.
- Monzo Plus: £5 monthly fee adding credit tracking features.
- Monzo Premium: £15 monthly fee including travel insurance.
Features that matter for immigrants:
- Instant sort code generation for immediate salary payments.
- Salary Sorter tool automatically isolates rent and savings.
- Free setups for direct debits and standing orders.
Downsides:
- Digital-only service structure with no branch network.
- ATM withdrawals abroad capped at £200 fee-free monthly.
- Cash deposits incur a small fee at PayPoint locations.
4. Barclays — Best high-street bank for skilled worker visa holders
Why immigrants choose it:
- Specialised pathways for Skilled Worker and Student visas.
- Accepts official employer confirmation letters as address proof.
- Branch appointments available if digital onboarding fails.
Accounts to consider:
- Barclays Bank Account: Standard fee-free daily current account.
- Barclays Basic Account: Tailored for individuals with thin credit files.
- Barclays International Account: Built for high-value asset transfers.
Features that matter:
- Widespread branch network for cash and official drafts.
- App-generated bank statements formally accepted by the Home Office.
- Stronger institutional weight for securing mobile phone contracts.
Downsides:
- Basic account limits contactless transactions and lacks overdrafts initially.
5. Revolut — Best for instant multi-currency needs
Why immigrants choose it for the UK:
- Fully licensed UK bank status ensures complete deposit protection.
- Accounts can be opened pre-arrival using your home country address.
Accounts to consider inside Revolut:
- Standard: Free account providing basic multi-currency tools.
- Plus: £3.99 monthly fee featuring disposable virtual cards.
- Premium: £7.99 monthly fee with unlimited currency exchange.
Features that matter:
- Hold and convert over 30 global currencies seamlessly.
- Instant local UK account numbers and European IBANs.
- Virtual cards facilitate immediate rental and NHS surcharge payments.
Downsides:
- Not always treated as a “real bank” by some UK legacy institutions.
What documents do immigrants need to open a UK bank account?
Requirements vary between banks and account types, but commonly requested documents include:
- Proof of Identity:
-
- Valid international passport.
- Biometric Residence Permit (BRP) or digital share code.
-
- Proof of Address:
- Official utility bills or council tax statements.
- Signed tenancy agreements or UK university enrolment letters.
- Qualifying introductory letters from employers or global financial entities.
Can immigrants open a UK bank account without proof of address?
Possibly, but it depends on the bank, the account and the documents available. Some providers accept alternatives to household bills, while others may require additional verification.
If you are refused a standard current account, ask whether you qualify for a basic bank account. These accounts are designed for people who do not qualify for some standard banking products. They generally allow customers to receive wages, pay bills and withdraw cash but do not provide an overdraft.
Opening an account is also separate from qualifying for credit. Having a current account does not automatically make you eligible for a credit card, loan or overdraft.
Which UK bank should you choose?
For immigrants settling in Britain, the most useful account is not necessarily the one with the longest feature list. It is the one that offers options based on usage reliability and maintenance affordability.
This guide is for general information and is not financial advice. Eligibility and account terms can change.
Monzo enters Nigeria’s remittance market, turning up the heat on African fintechs
These Four UK Visa Pathways Are Available to Tech Talents in AI