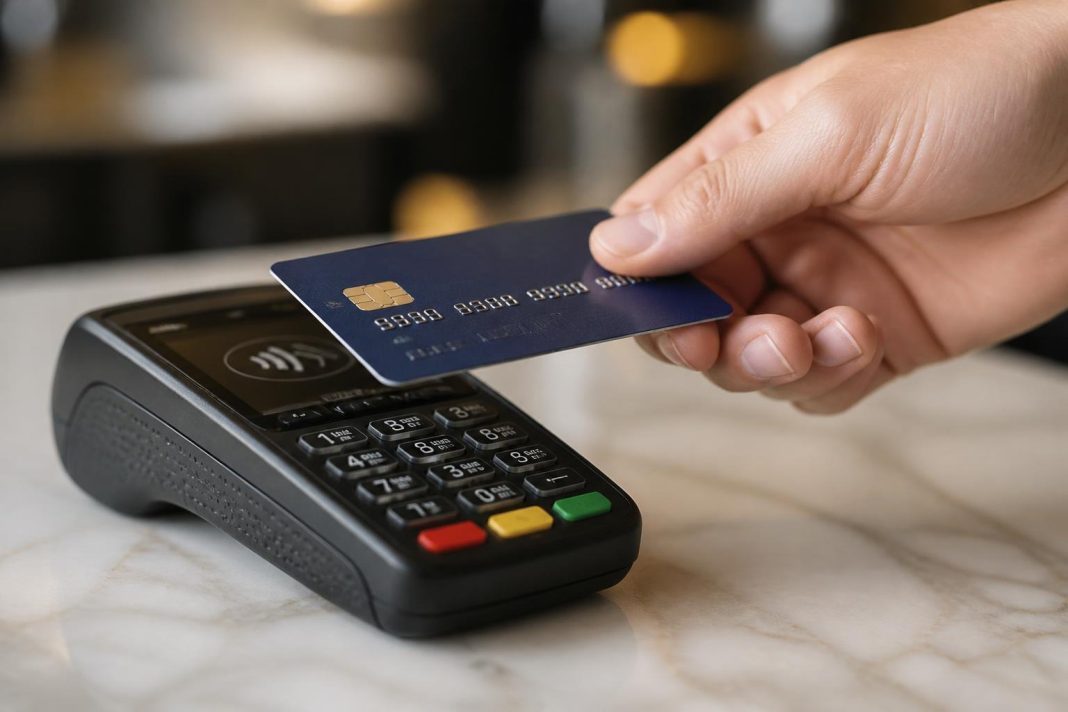

South African card-linked installment platform Float has reported that its UK expansion is outstripping its domestic growth trajectory. The company entered the UK market in July—marking its first international expansion—enabling consumers to split retail purchases into up to 24 interest-free monthly installments by utilising the existing credit limit on their Visa or Mastercard credit cards.
Founded in 2020 by Alex Forsyth-Thomson, Float differentiates itself from traditional Buy Now, Pay Later (BNPL) startups through its plug-and-play architecture. The UK already boasts a mature credit ecosystem with over 55 million active credit cards in circulation. Float allows these consumers to optimise their existing cards, unlocking hundreds of billions in untapped, pre-approved credit lines while saving them significant sums in revolving credit card interest.
Float has raised over $15.8 million (R280 million) in combined equity and debt funding. This includes an initial $11 million facility anchored by Standard Bank Corporate and Investment Banking, followed by a $2.6 million (R46 million) equity funding round co-led by South African venture capital fund Invenfin and SAAD Investment Holdings, with backing from Platform Investment Partners and advisory support from Lighthouse Venture Partners.
“We built Float to solve the other half of that equation: enabling merchants to offer their existing credit-card-holding customers more time to repay, rather than giving them a new loan and another app to get through checkout. These shoppers don’t need more credit. They need more time to pay,” Alex told The Fintech Times.
Unlike legacy BNPL providers that require consumer credit checks, lengthy sign-ups, and identity verification (KYC), Float eliminates these hurdles. Float’s B2B2C commercial model shifts monetisation away from consumer interest or late fees, relying instead on merchant-side transaction fees. When a shopper purchases an item using Float, the platform secures the full purchase amount by placing a temporary hold on the consumer’s existing credit card limit. Float then pays the merchant upfront, helping e-commerce platforms drive higher conversion rates and average order values. The customer’s card issuer automatically releases the held funds in monthly tranches as the installments are paid off, shifting the repayment settlement directly to the bank and eliminating consumer default risk for Float.
According to Float’s internal merchant metrics, businesses integrating the platform experience an average 134% surge in Average Order Value (AOV). Float has integrated with more than 2,200 stores, a few of which include major brands such as Samsung, Diesel, Reebok, The North Face, Trek Bikes, and official Apple resellers.
Backed by the UK Government’s Global Entrepreneur Programme, Float did not have to blend in the country’s heavily saturated payments market dominated by giants like Klarna and Clearpay. Float has been recognised in the UK as a finalist for Best eCommerce Payment Solution at the eCommerce Awards London and shortlisted at the PAY360 Awards.
While South Africa has a robust credit economy, with approximately 5.2 million credit cardholders and an average credit card balance sitting at R25 thousand in unused credit, the rest of sub-Saharan Africa is fundamentally uncarded. This makes it impossible to replicate across the wider continent. In major fintech markets like Kenya, Nigeria, and Ghana, formal credit card penetration hovers in the low single digits. Instead, these economies have evolved around mobile money wallets such as Safaricom’s M-Pesa or MTN Mobile Money.
Float plans to expand to more countries, however, its service is uniquely tied to countries with active credit card usage. “Beyond the UK, our technology runs on global credit card rails, which makes the model extremely portable to any market with meaningful credit card penetration. We haven’t ruled out expanding further, and our ambition is bigger than any single country: to redefine the way the world pays with credit,” Alex revealed.