
South African fintech Float chose the UK as its first international market after building its card-linked instalment product across more than 2,200 stores at home.
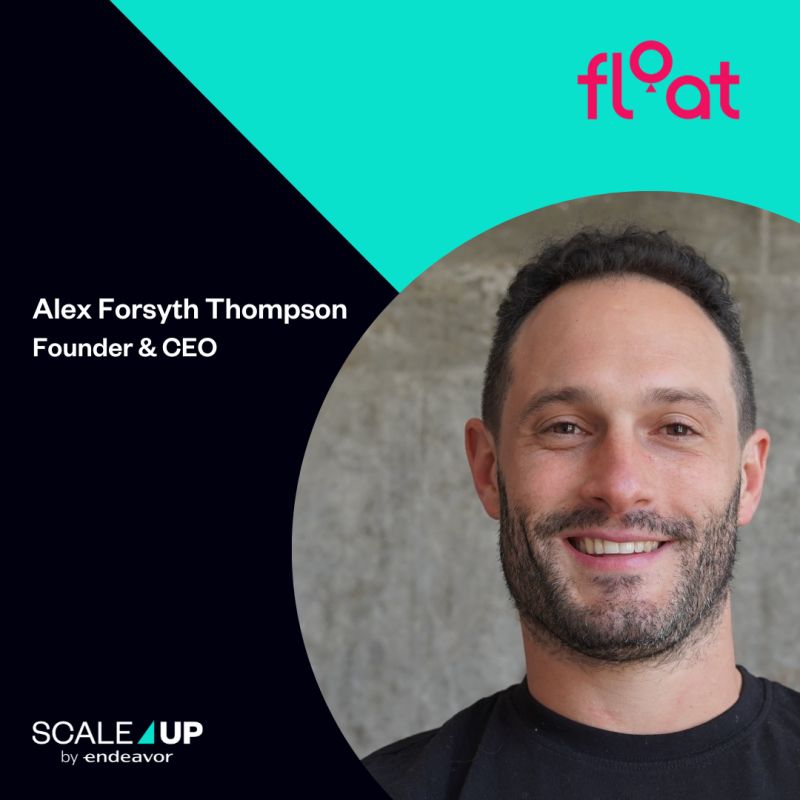
Founded in 2021 by Alex Forsyth-Thompson, Float allows shoppers to split purchases into interest-free monthly instalments using credit already available on an existing Visa or Mastercard credit card. Customers do not take out a new loan, complete another credit application or download a separate app.
The company launched in Britain in July, entering one of Europe’s most competitive payments markets before expanding elsewhere in Africa or into the US.
Float’s UK expansion was supported by the UK government’s Global Entrepreneur Programme, which works with high-growth international companies looking to establish operations in Britain.
Why Britain came first
Forsyth-Thompson has argued that South Africa’s payments sector gave Float a strong base for competing internationally. The company’s existing South African merchant network includes Samsung, iStore, The North Face and other retailers.
Britain also offers a sizeable addressable market. Float says its technology is compatible with more than 55 million UK credit cards, giving merchants another way to offer instalments without extending new credit to customers.
The company’s UK operation is already developing faster than its South African business did at the same stage. In an interview with The Fintech Times published on 24 September, Forsyth-Thompson said: “We’re already ahead of where we were at the same stage of our South African journey,” adding that this “says a lot about how ready this market is for the model.”
Float has also been using London to introduce the product directly to British retailers. Forsyth-Thompson spoke at eCommerce Expo at ExCeL London on 23 September, discussing card-linked instalments and their potential impact on basket sizes and conversion.
An African fintech exporting its model
Float’s move reverses a familiar direction of travel in African fintech, where international technologies and business models are often adapted for local markets. In this case, a payments product developed in South Africa is being taken into Britain as the company’s first step abroad.
The UK expansion will test whether Float can reproduce the merchant adoption it has achieved in South Africa while competing in a mature market already served by credit cards and established buy-now-pay-later providers.